Our archives on Bank Results

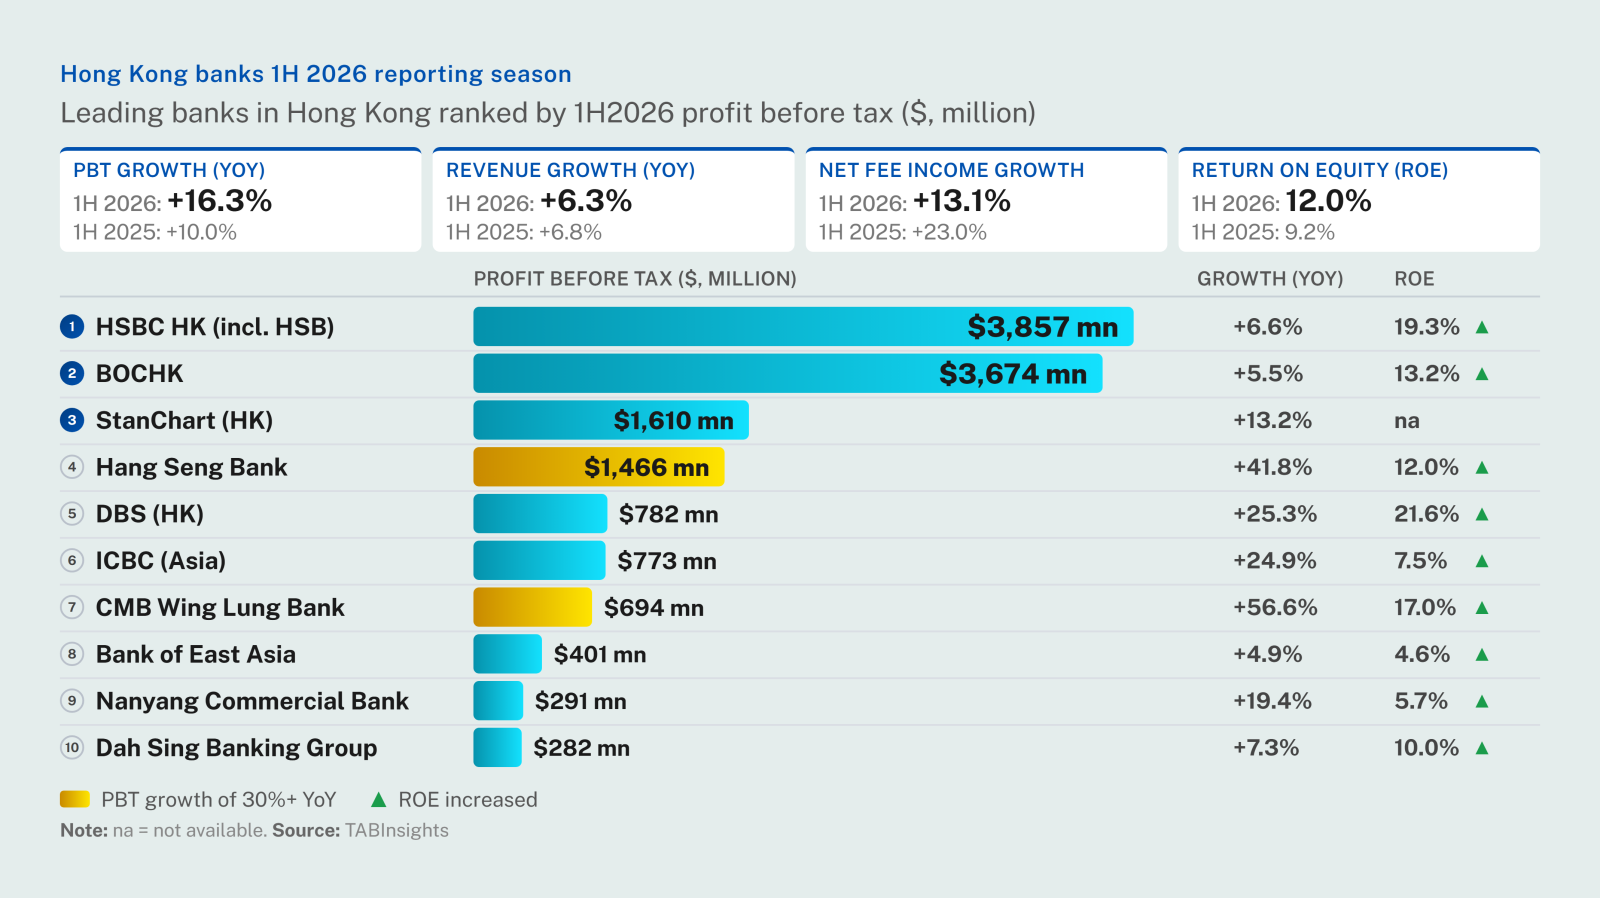
Hong Kong’s leading banks accelerated median pre-tax profit growth to 16.3% year on year (YOY) in the first half of 2026 (1H2026). HSBC Hong Kong (including Hang Seng Bank) continued to lead the large-scale bank segment in earnings scale and returns, while DBS Hong Kong and CMB Wing Lung Bank delivered stronger growth momentum and profitability among mid-sized banks. Across the sector, growth was increasingly supported by fee-based businesses, wealth management, cross-border activity and digitally-enabled customer engagement, which emerged as key drivers of revenue expansion.

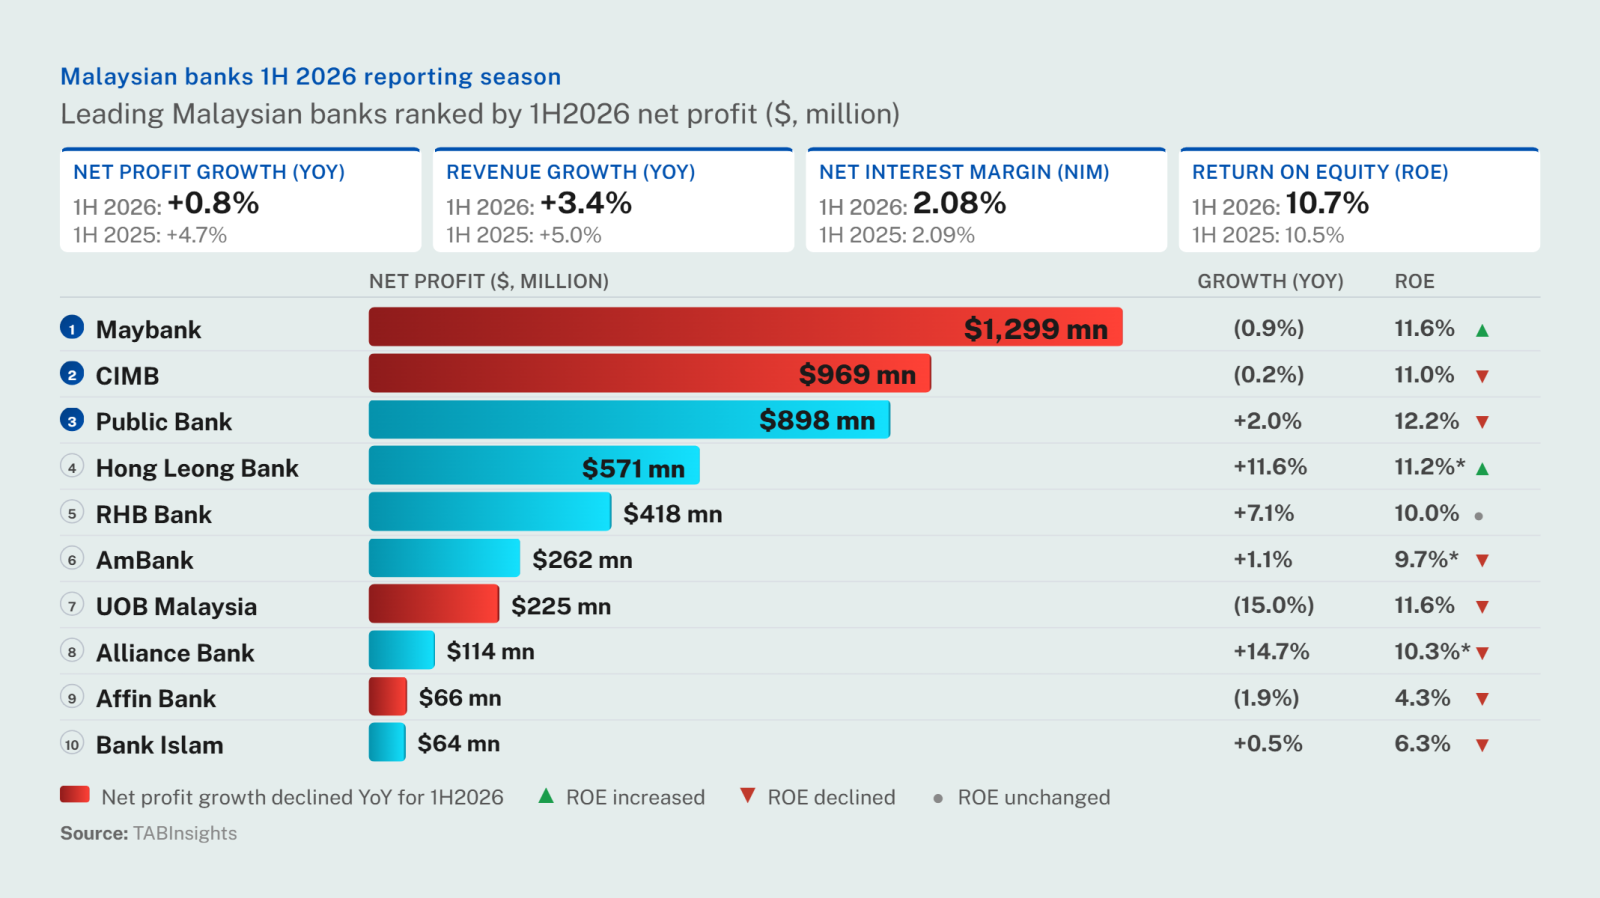
Malaysian banks' net profit was broadly flat in the first half of 2026 (1H2026), but their core lending businesses did not drive the result. Retail banking profit fell or stalled at most large groups, while corporate banking profit was likely flat. Treasury and markets income, wealth management and fund management provided most of the growth. Hong Leong Bank and Alliance Bank were the clearest exceptions, with broad-based operating strength.
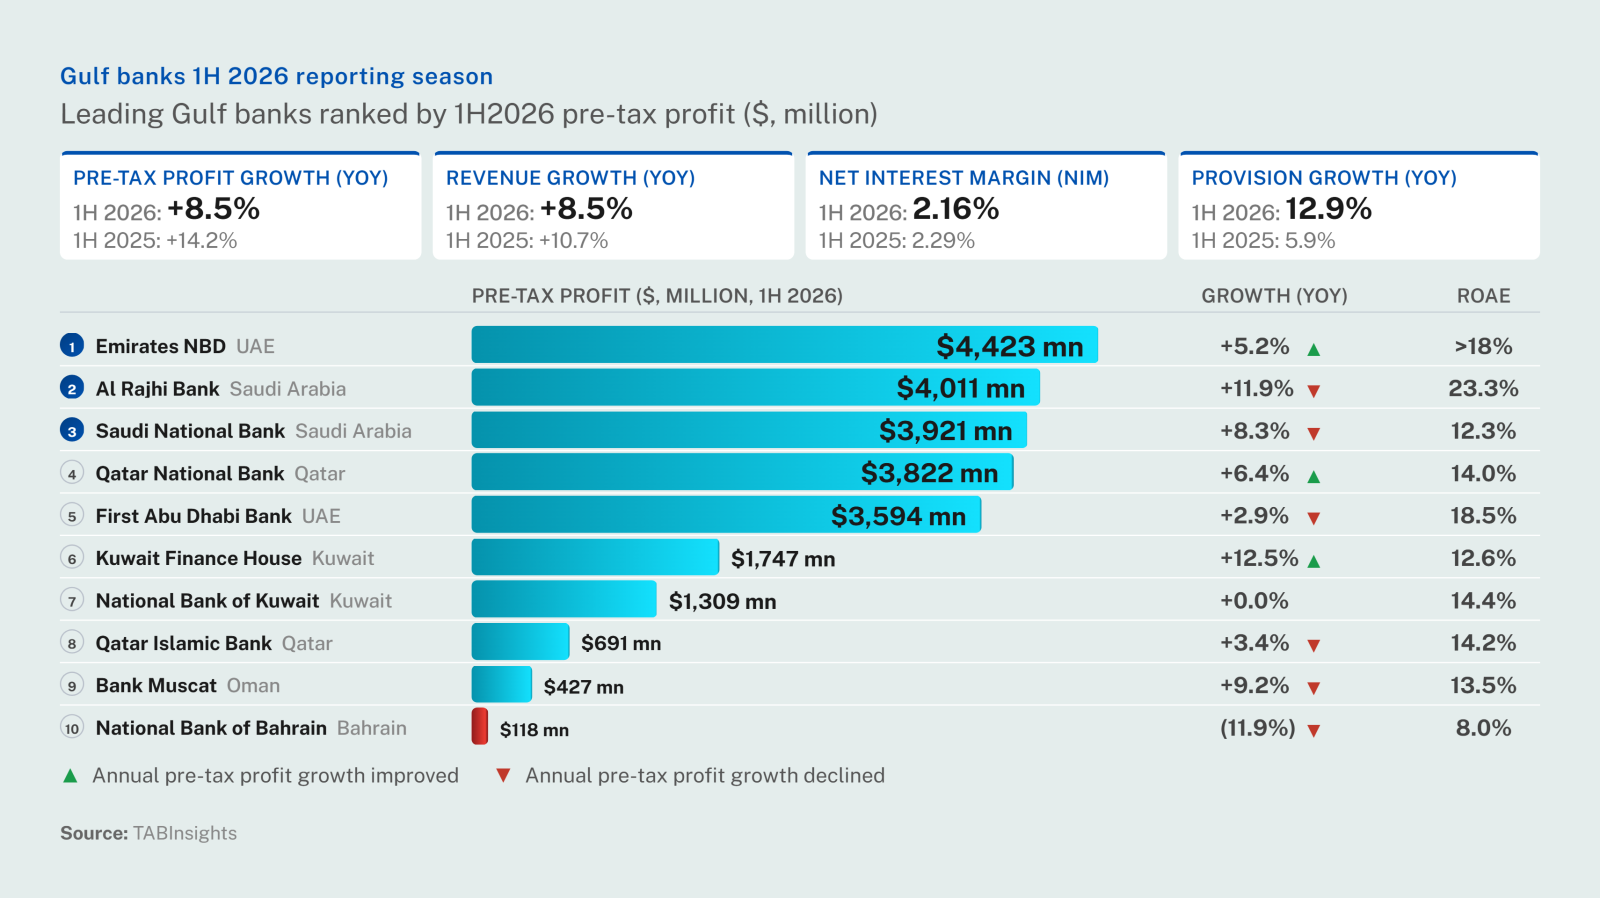
Gulf banks saw earnings momentum weaken in the first half of 2026 as slower revenue growth, narrower margins and higher provisions offset resilient credit quality. Emirates NBD, Kuwait Finance House and Qatar National Bank outperformed, while the Iran conflict amplified differences across markets and raised the stakes for loan growth, funding and credit costs in the second half of the year.

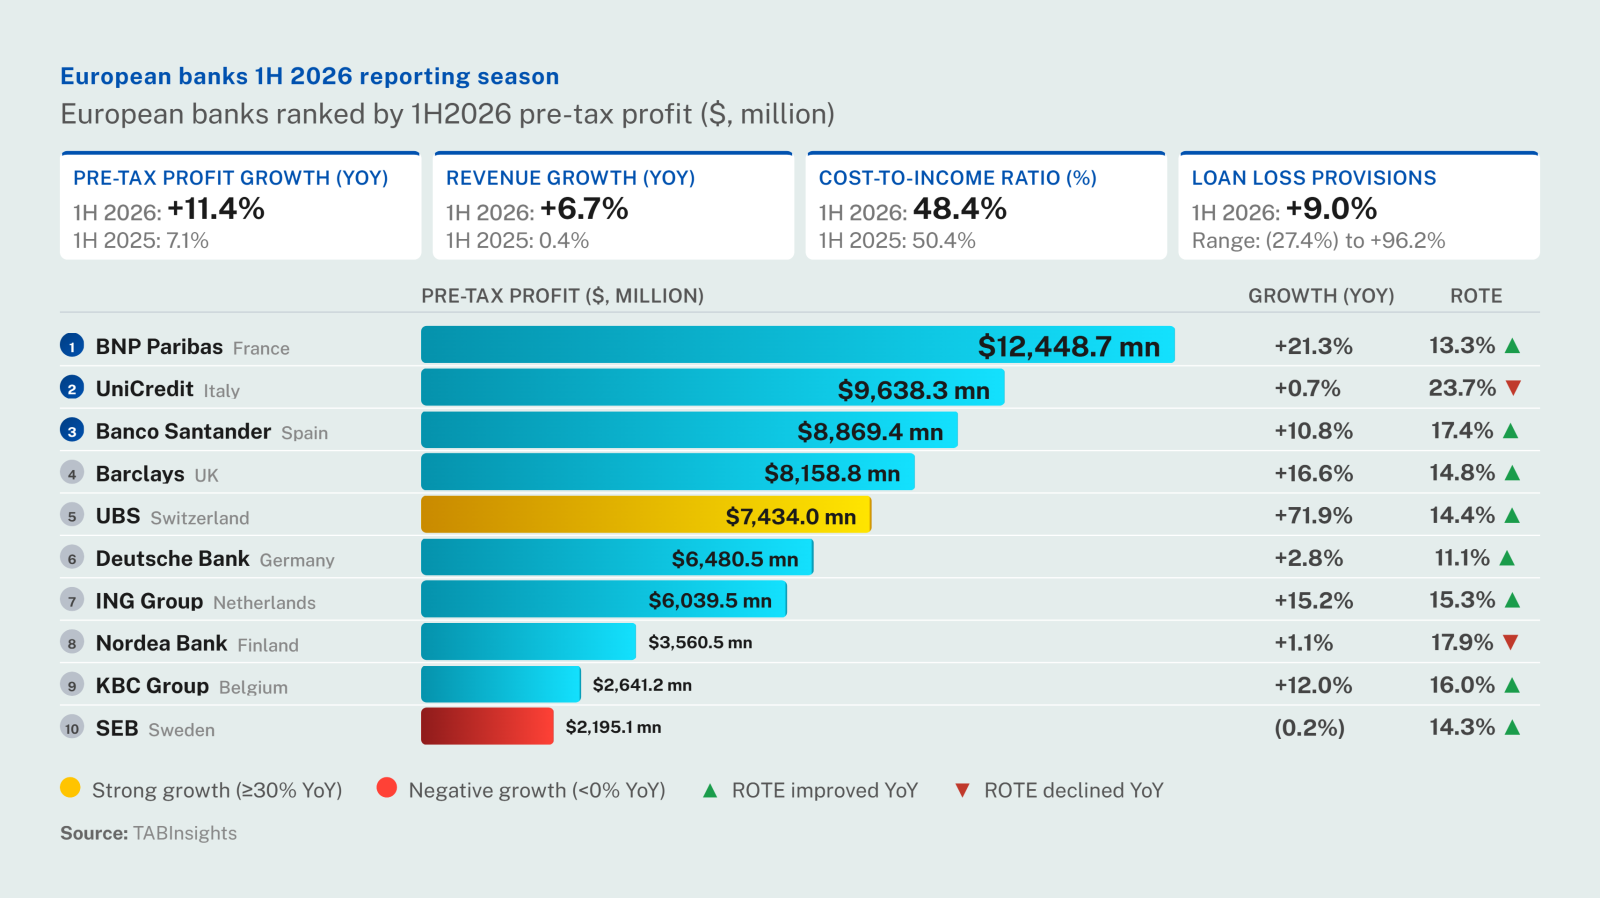
Europe’s largest banks by country showed surprising resilience in the first half of 2026, with broad-based growth across their business segments. UBS, Barclays and BNP Paribas stood out, although part of their results were boosted by corporate-centre gains, treasury performance and exceptional items. Strong earnings prompted several banks to raise their full-year guidance and reconsider mergers and acquisitions

Exclusive benefits are on your way. Subscribe and enjoy the benefits.
Chat with us WhatsApp