Bank Results Jul 29
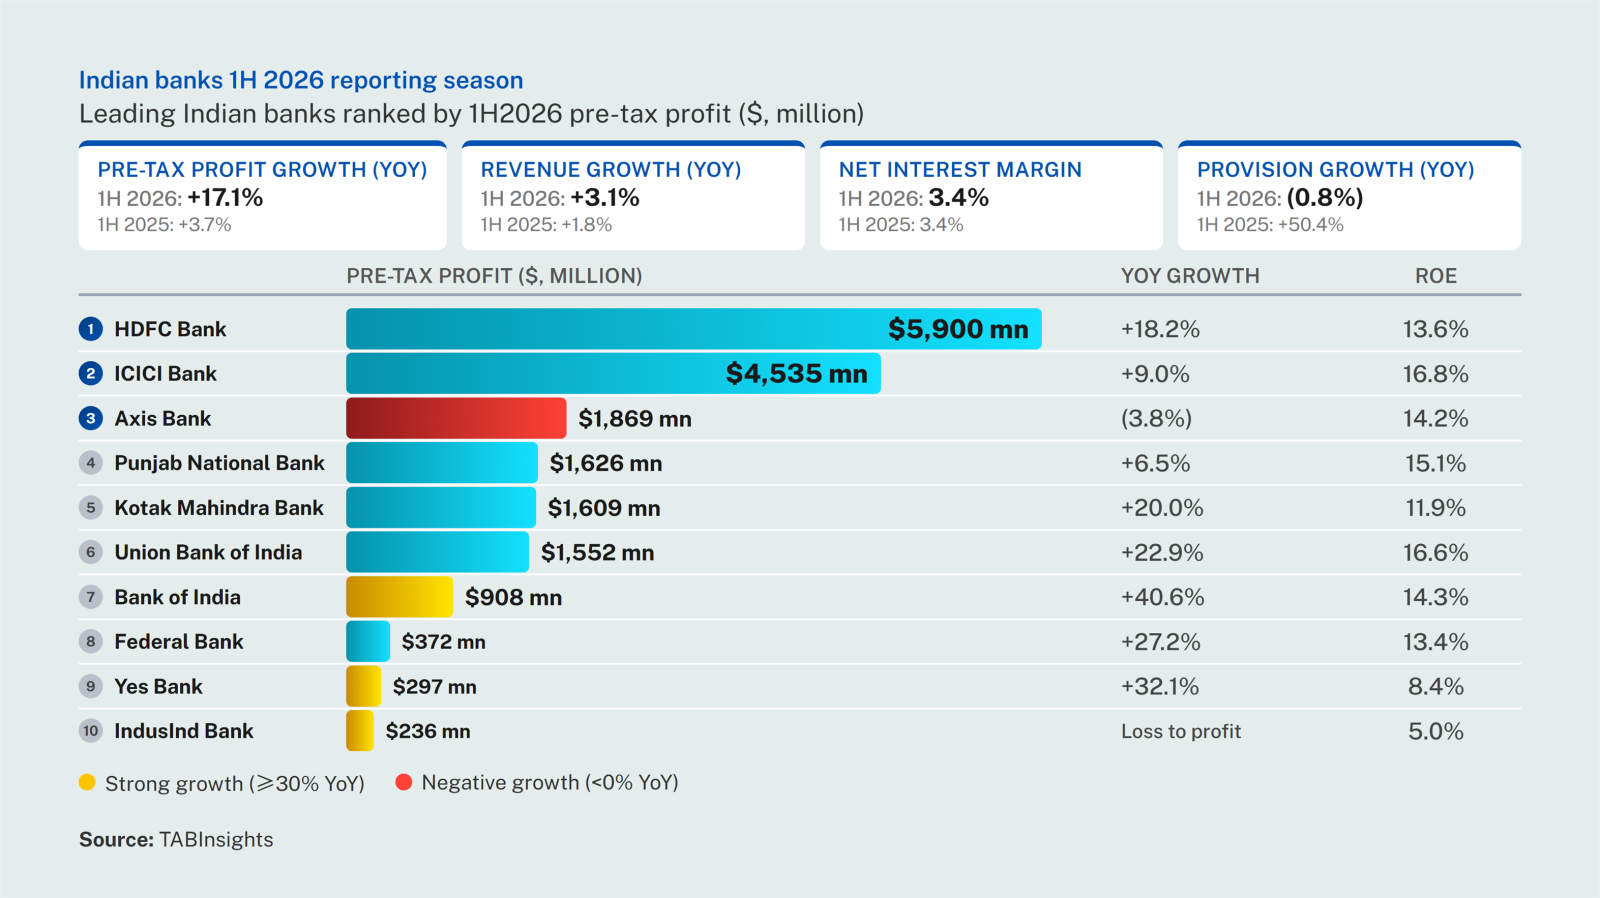
Indian lenders posted stronger first-half profits as lower loan provisions boosted earnings, but weak revenue growth and margin pressure point to a more challenging outlook.

Indian lenders posted stronger first-half profits as lower loan provisions boosted earnings, but weak revenue growth and margin pressure point to a more challenging outlook.
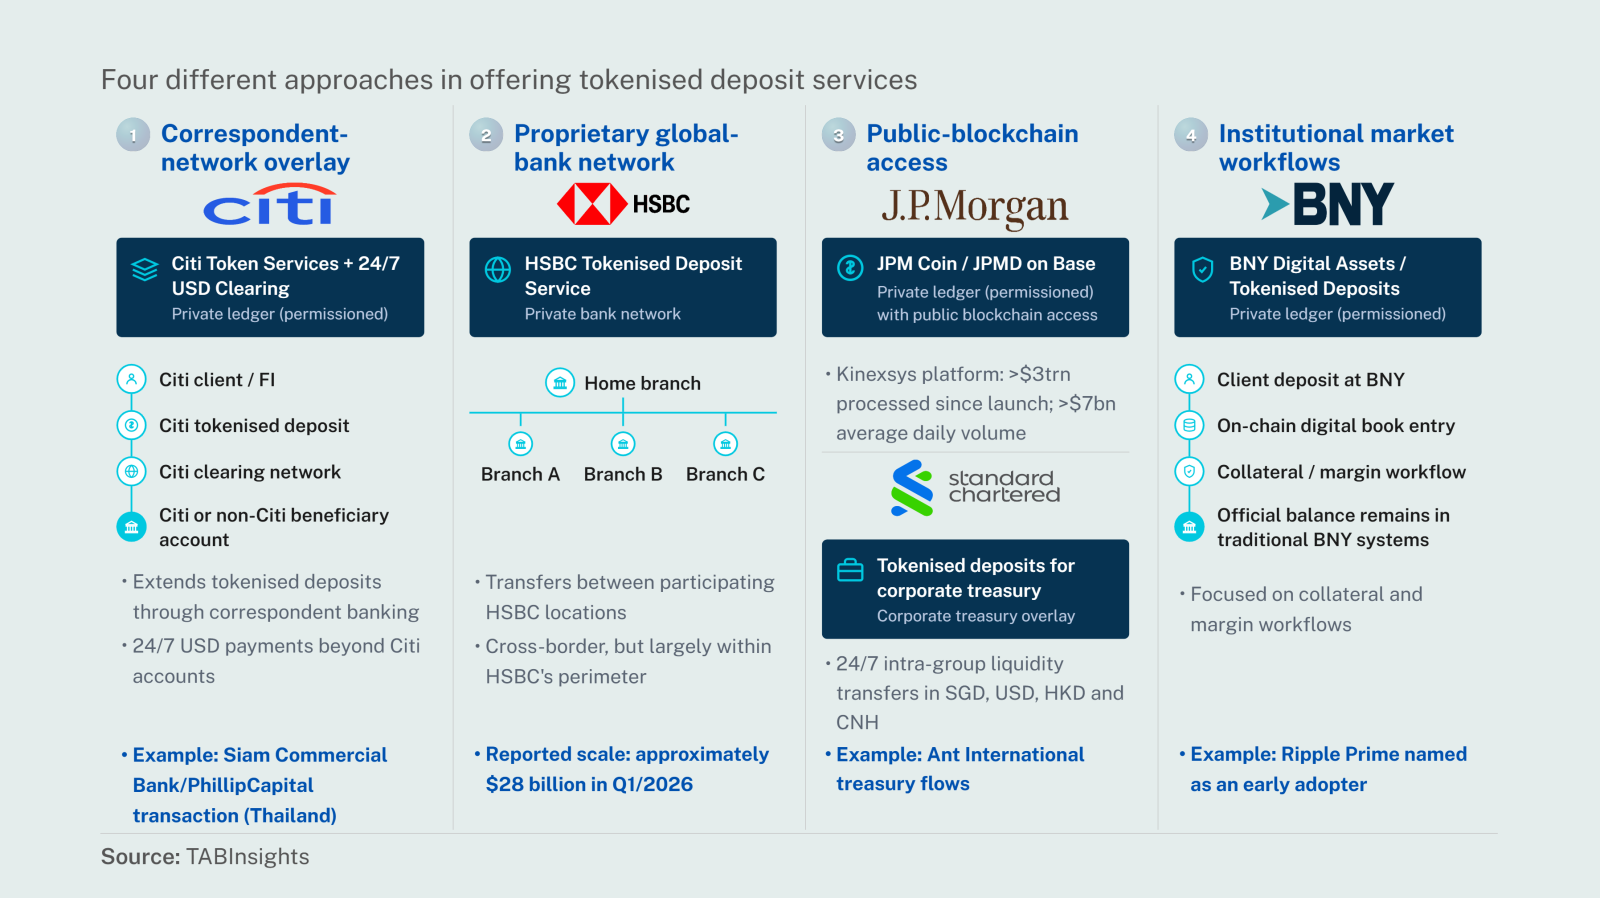
Siam Commercial Bank’s adoption of Citi’s integrated 24/7 USD Clearing and Token Services extends round-the-clock tokenised payments beyond Citi’s own accounts. But as HSBC, J.P. Morgan, Standard Chartered and BNY pursue alternative models, and shared ledgers gain momentum, the competition is shifting from first-mover advantage to interoperability and network scale.
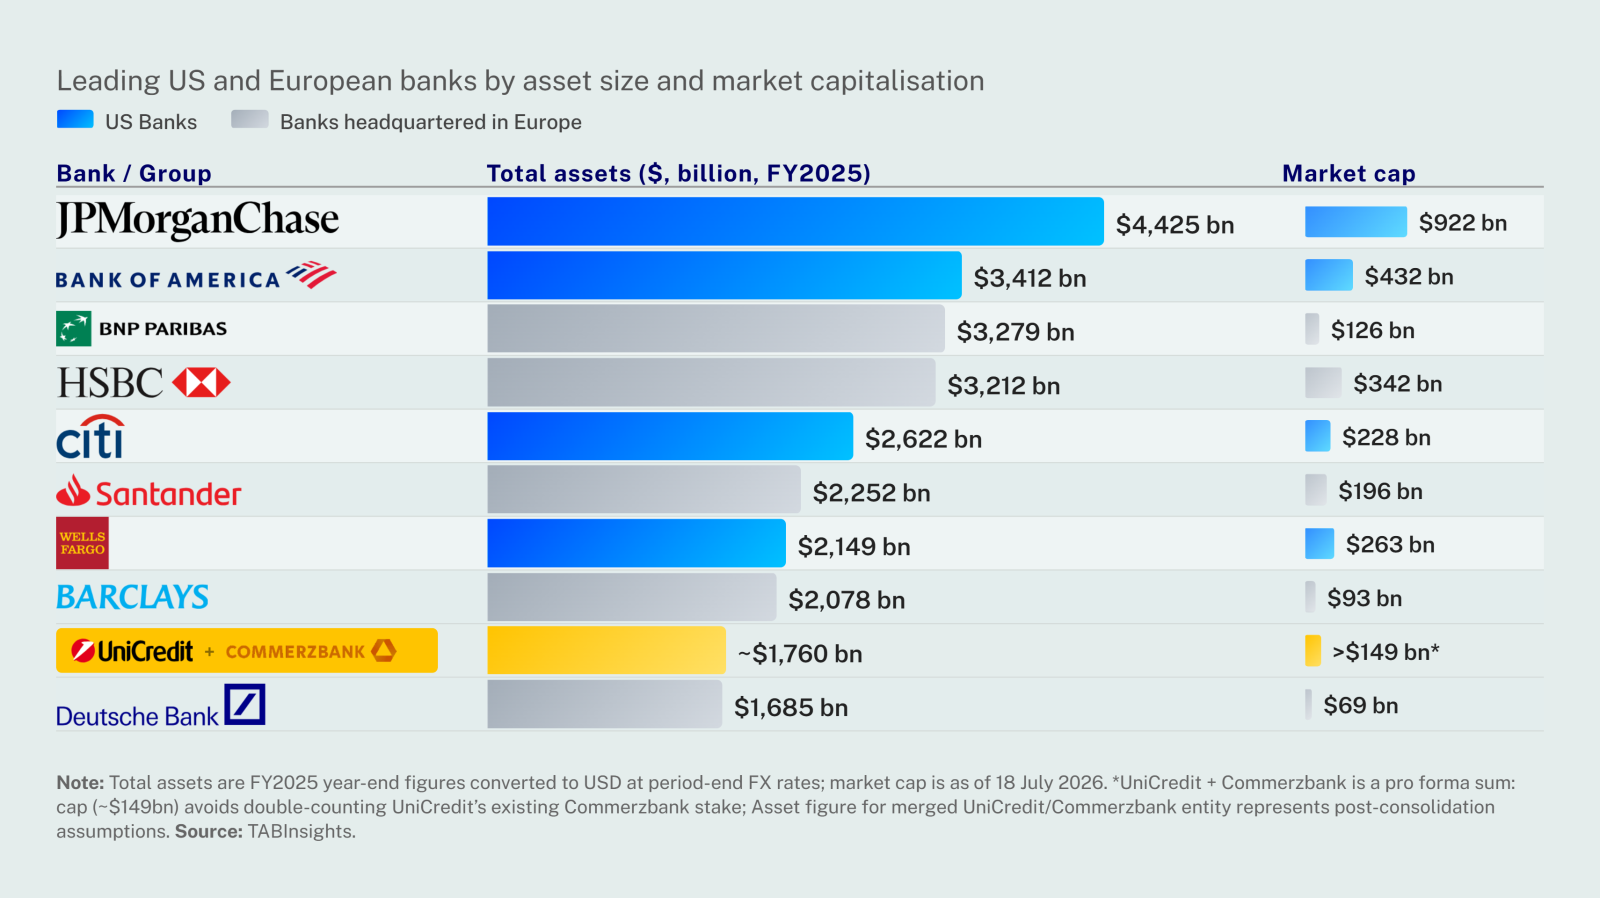
UniCredit’s path to taking full control of Commerzbank by the end of 2026 represents a decisive test of European banking consolidation, challenging political resistance and signalling that shareholder interests may increasingly outweigh national protectionism in shaping the region’s banking landscape. The resulting model would leave Commerzbank with a smaller, more focused international network designed primarily to support German, Polish and other European corporate clients rather than operate as a dispersed global lending franchise.
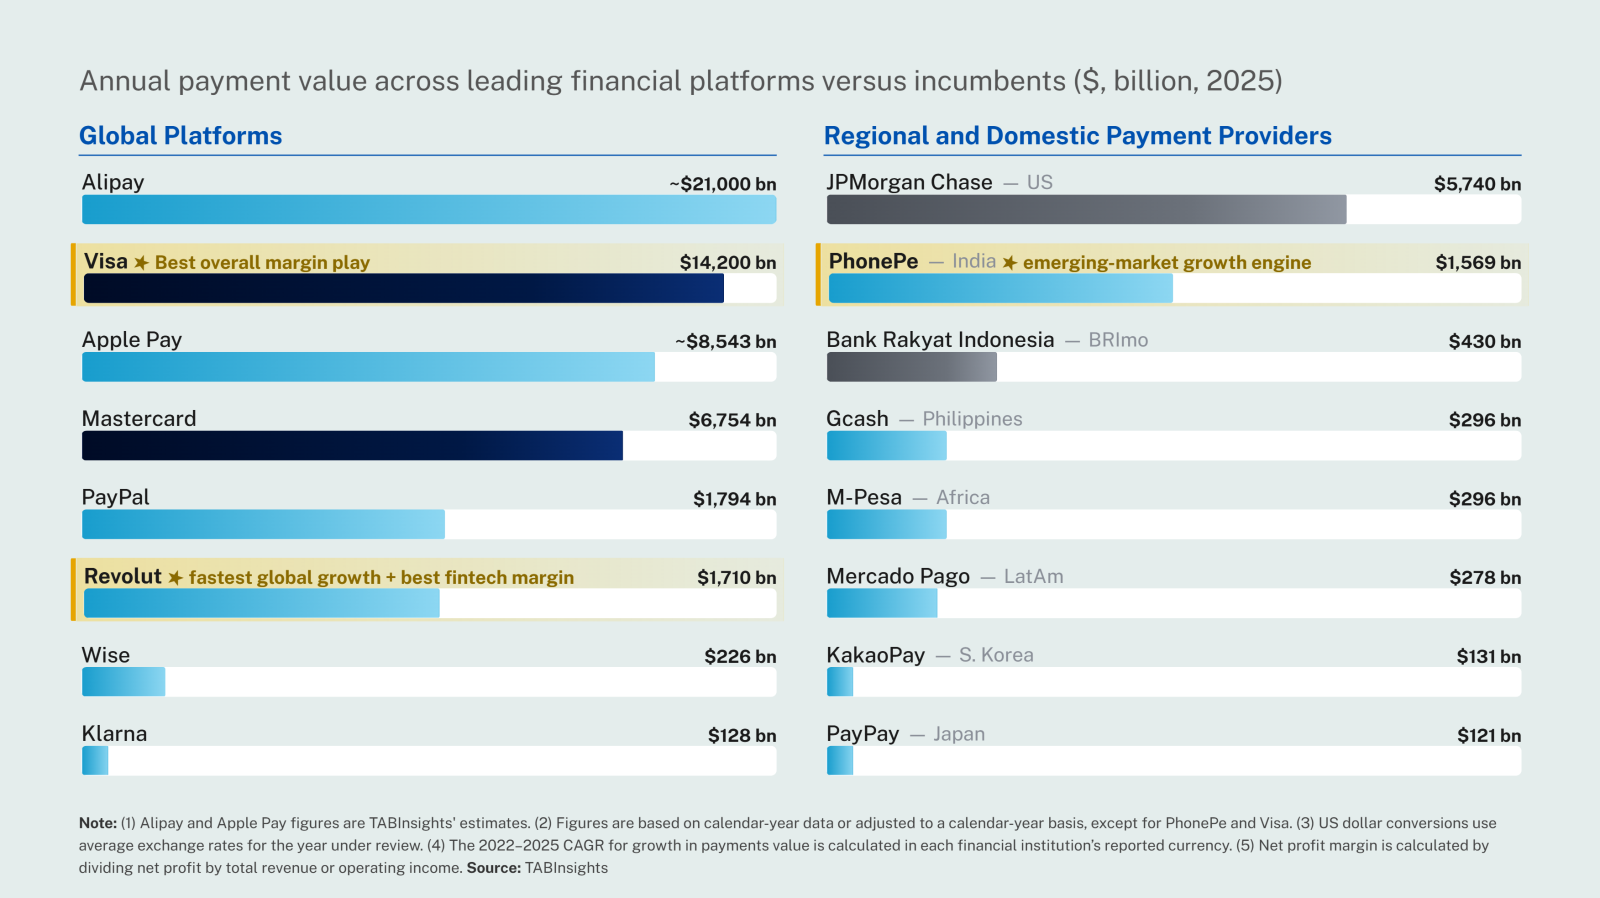
Fintech platforms have evolved from payment apps into formidable competitors to banks, using payments as a gateway to credit, savings, investments, insurance and merchant services, often without the cost and regulatory burden of a full banking licence. The world's largest platforms show that this model can deliver both enormous scale and, in most cases, strong profitability.
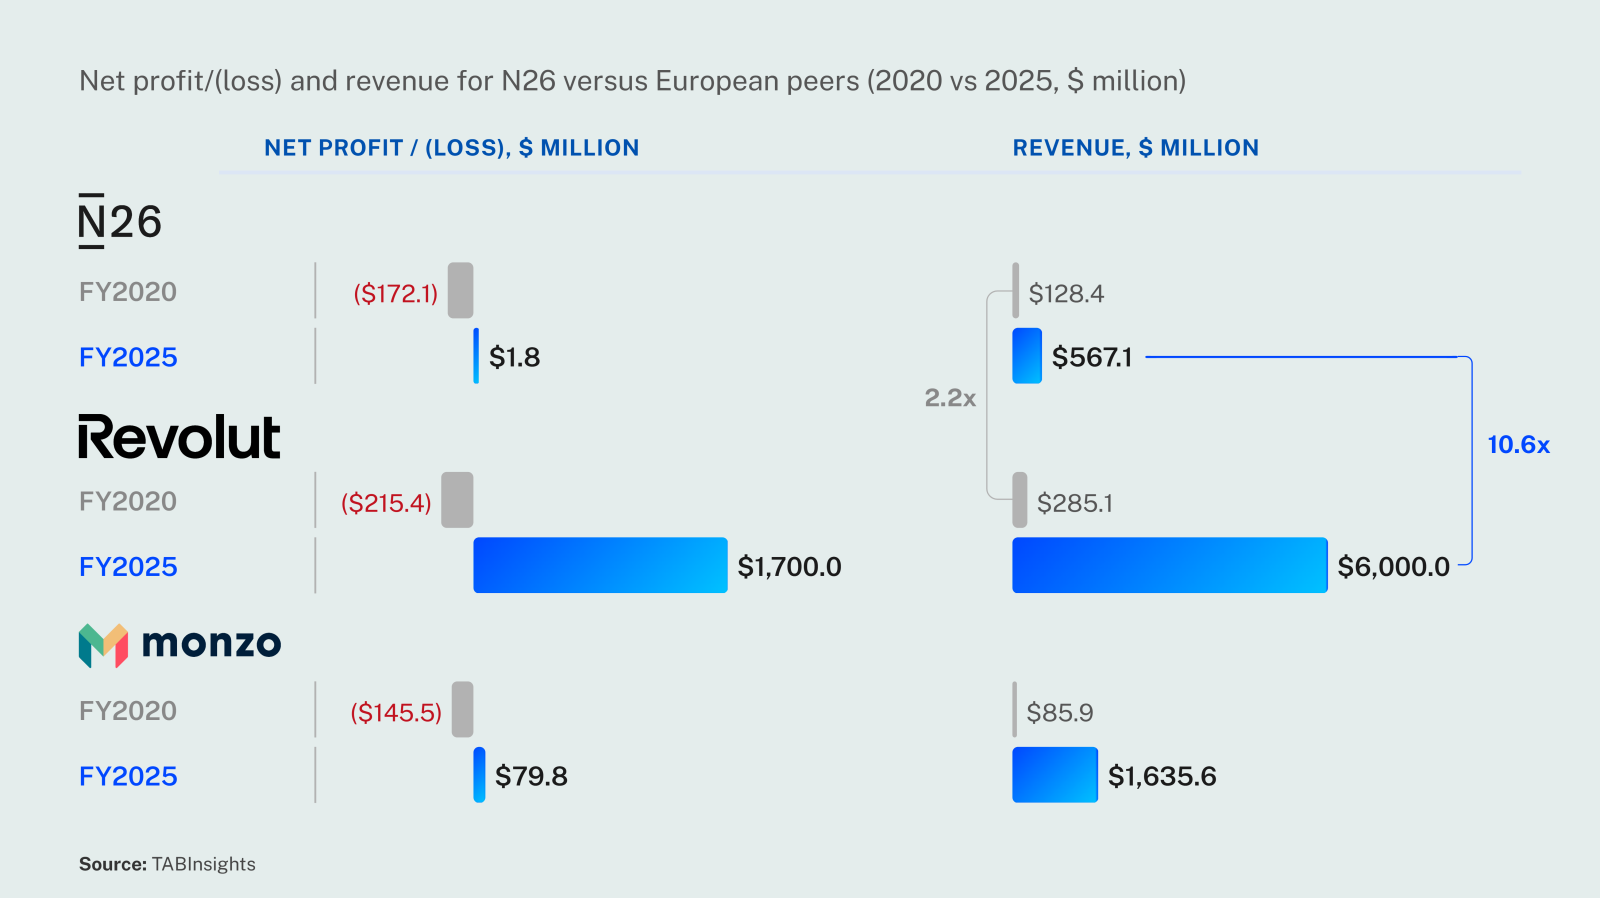
N26 delivered its first full-year net profit in 2025, but a decade of prioritising growth over bank-grade controls left the German fintech trailing European rivals, prompting a sweeping leadership overhaul.
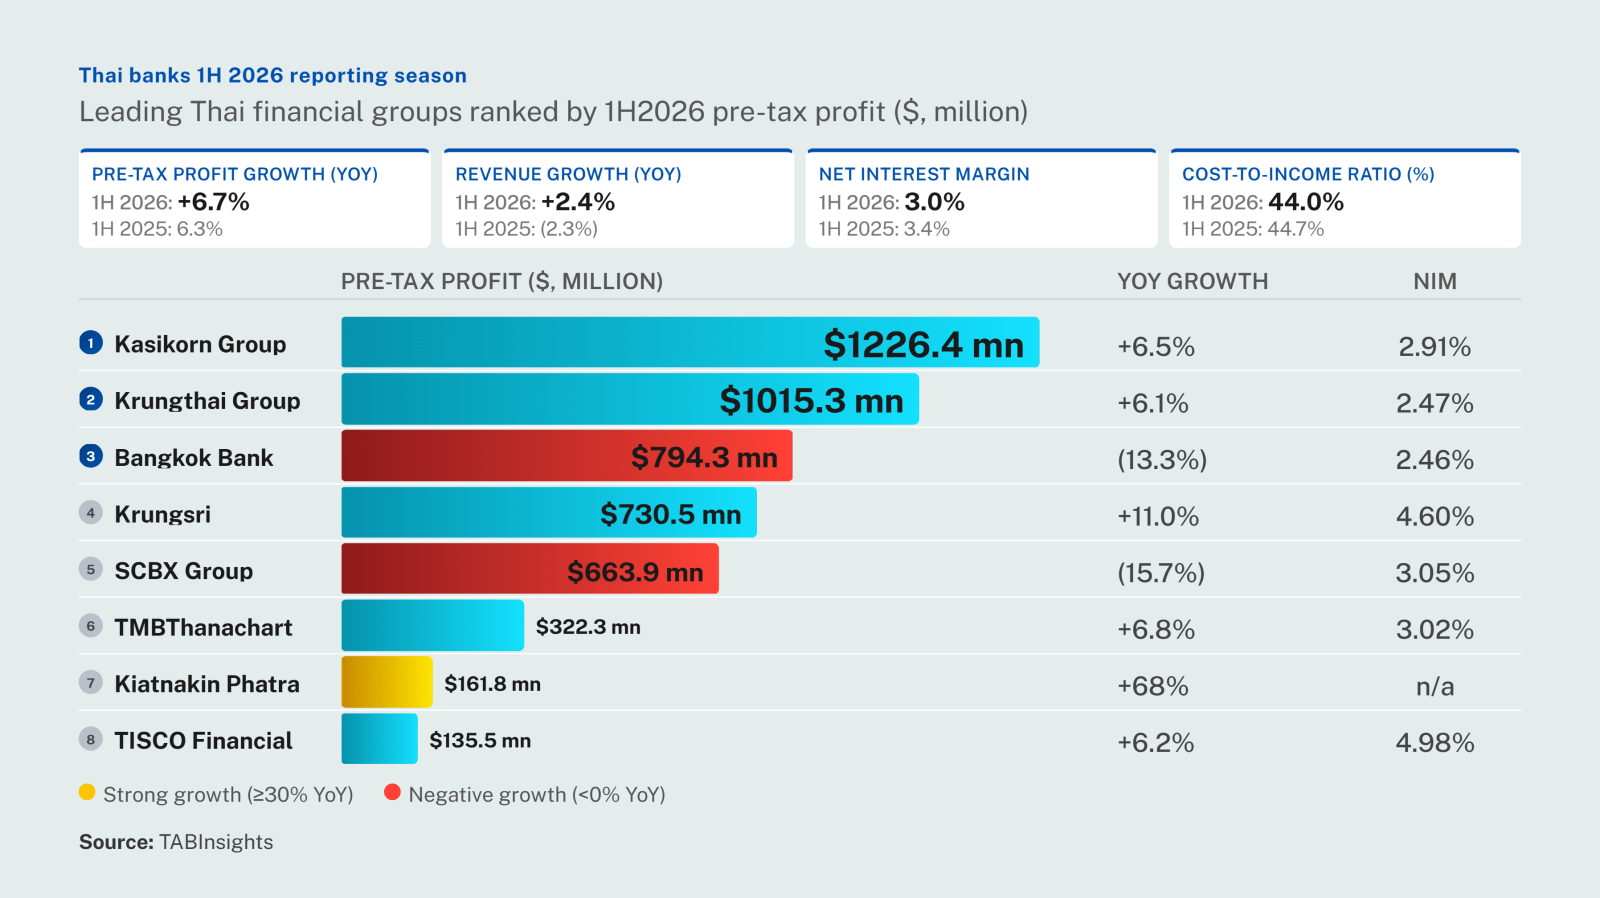
Thai financial players entered the lower-rate cycle in the first half of 2026 with strong balance sheets and capital positions, but the key differentiator was how effectively they repriced deposits as asset yields declined, rather than credit quality. Krungsri emerged as the best-performing financial institution among its peers.
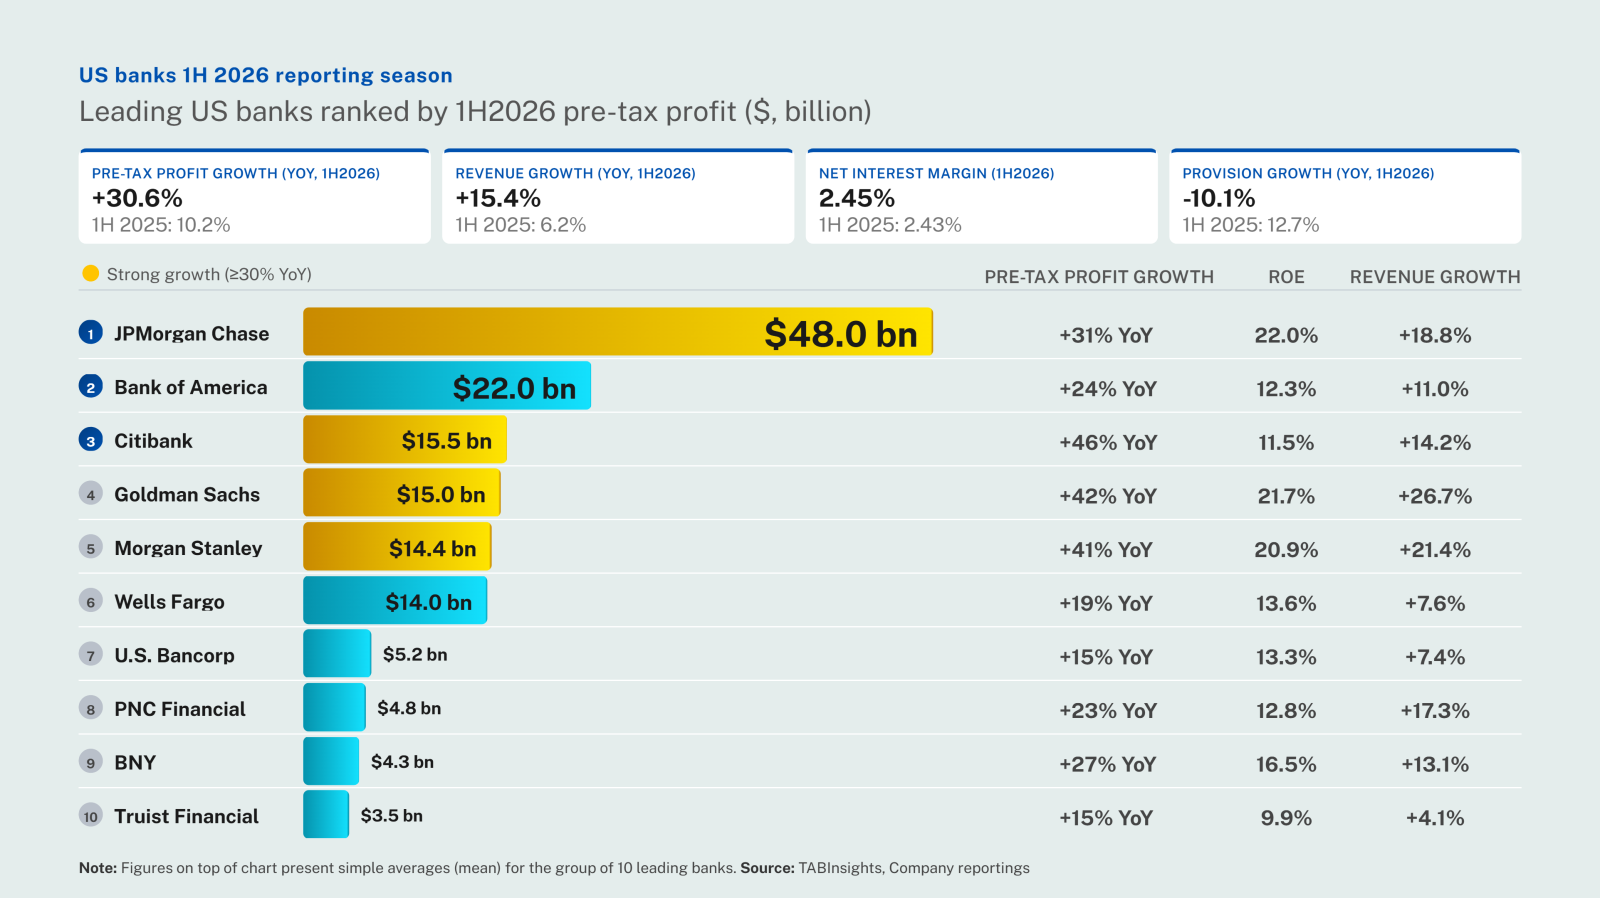
Robust capital markets activity and lower credit provisions lifted first-half earnings at leading US banks, but gains were concentrated among the largest, most diversified institutions. JPMorgan Chase led the group in absolute pre-tax profit, while limited margin expansion and slower revenue growth at regional lenders exposed a widening earnings divide.
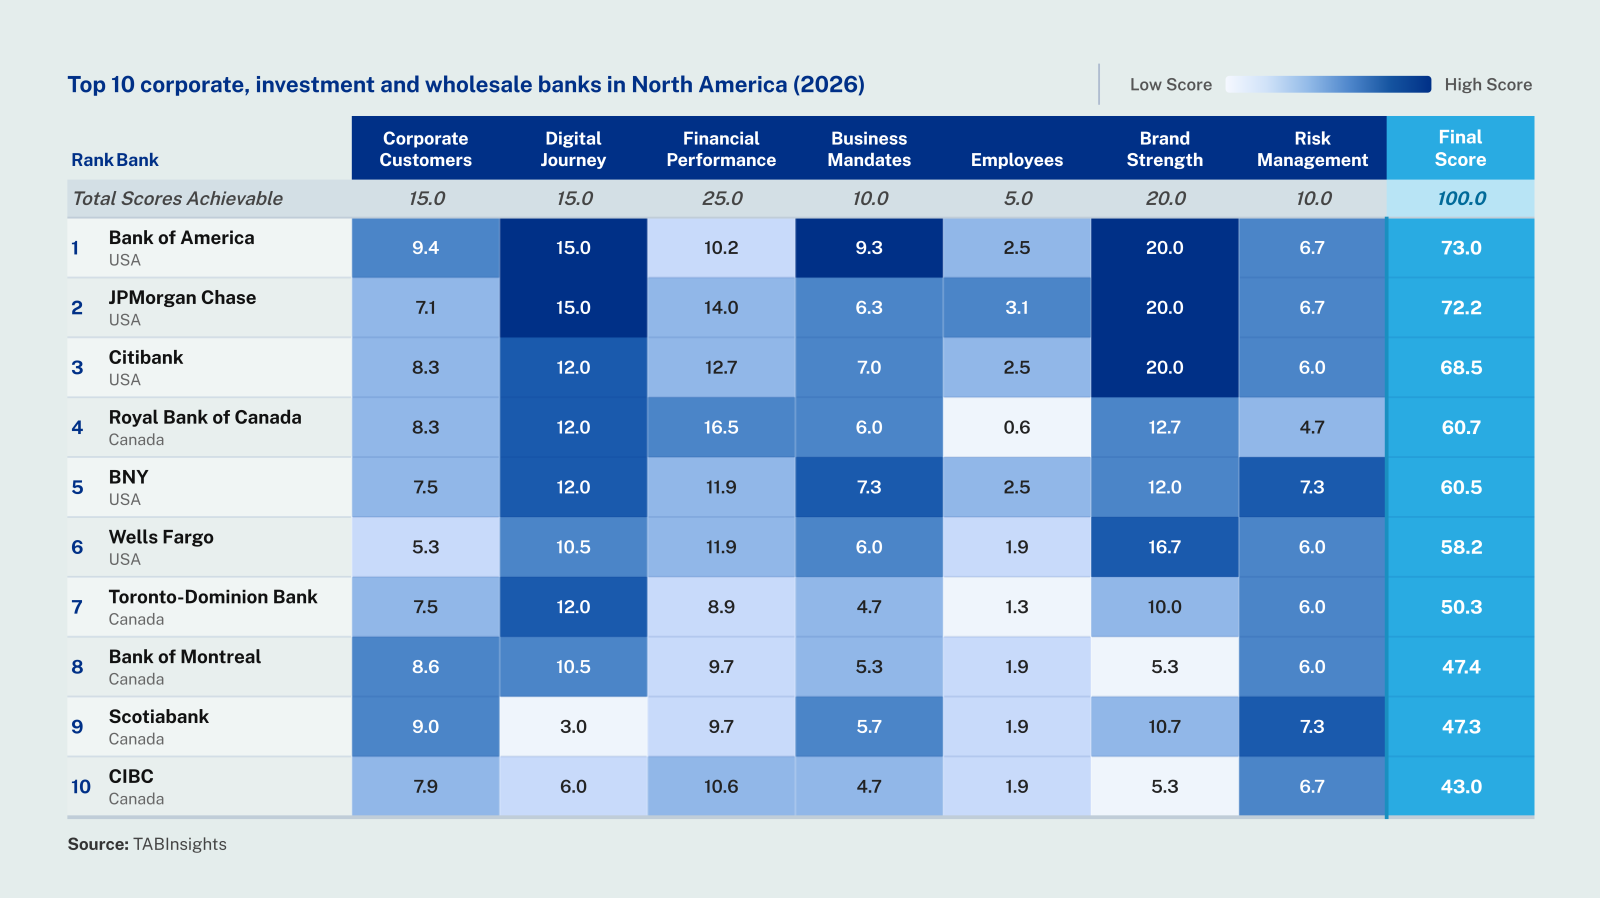
North America's leading corporate and investment banks retained their global dominance in 2025, although their performance revealed widening efficiency gaps as revenue growth, regulatory changes and remediation costs shaped results.
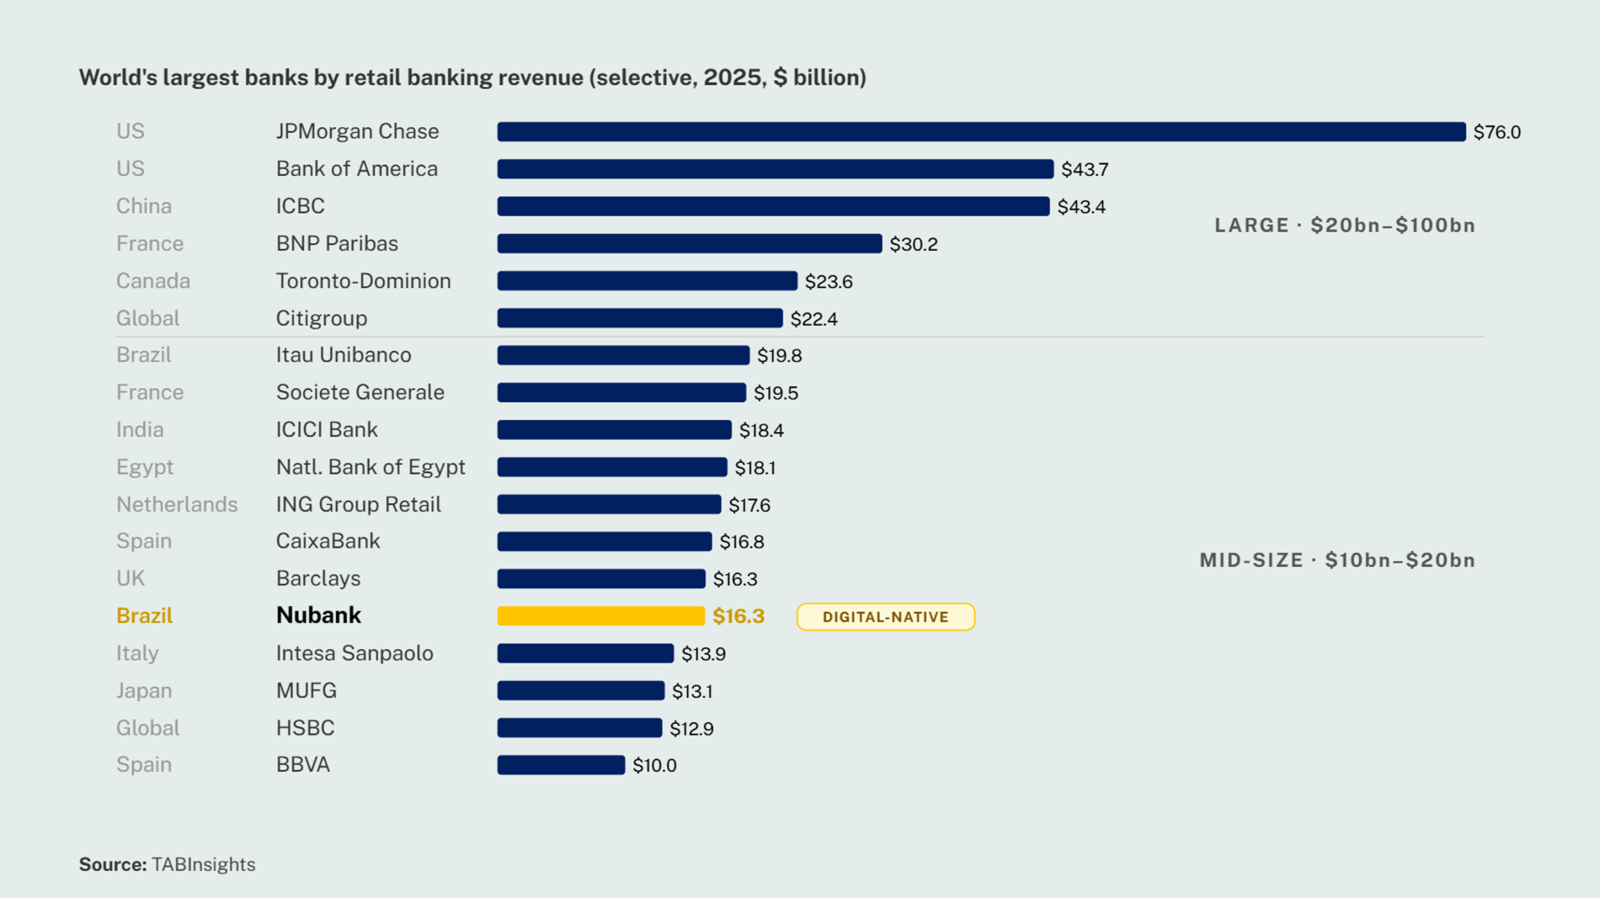
A decade ago, Nubank was a credit card start-up operating out of São Paulo. Today, at $16.3 billion in retail banking revenue (2025), it has surpassed HSBC and Standard Chartered’s global retail banking businesses and is on track to overtake Itaú Unibanco in Brazil in 2026 and Citigroup by 2027. What is emerging is not just rapid growth, but the early stages of a long-term strategy to build a global retail banking franchise.
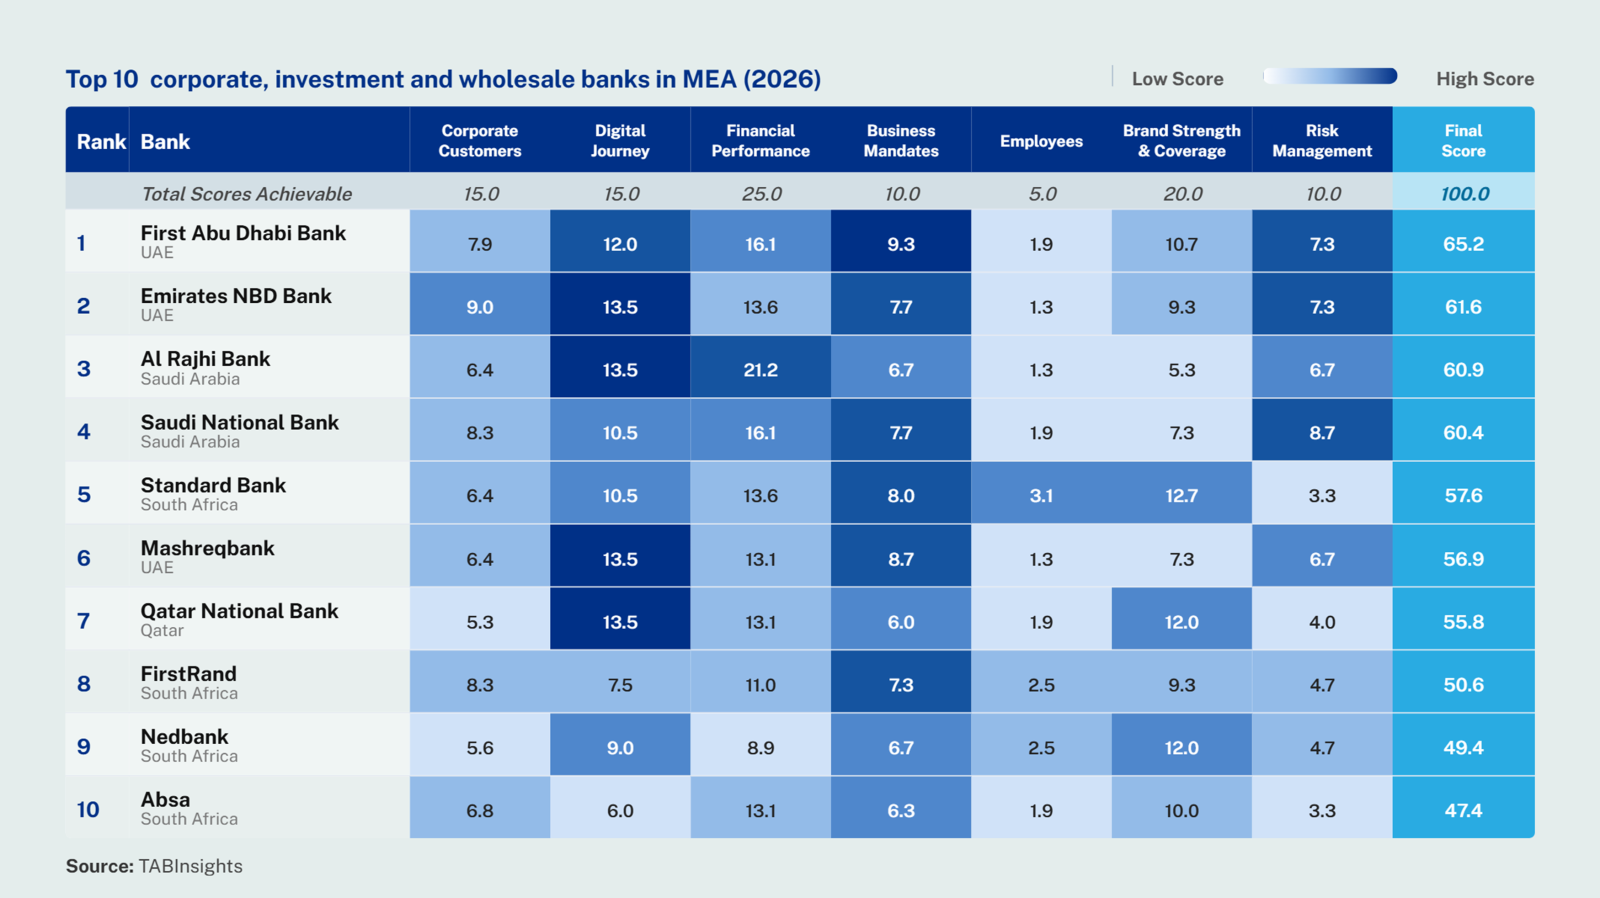
The 2026 ranking highlights how Gulf and African banks are pursuing different strategies to strengthen their corporate and wholesale franchises, with digital capability, regional connectivity, capital markets expertise and disciplined financial performance emerging as key competitive differentiators.
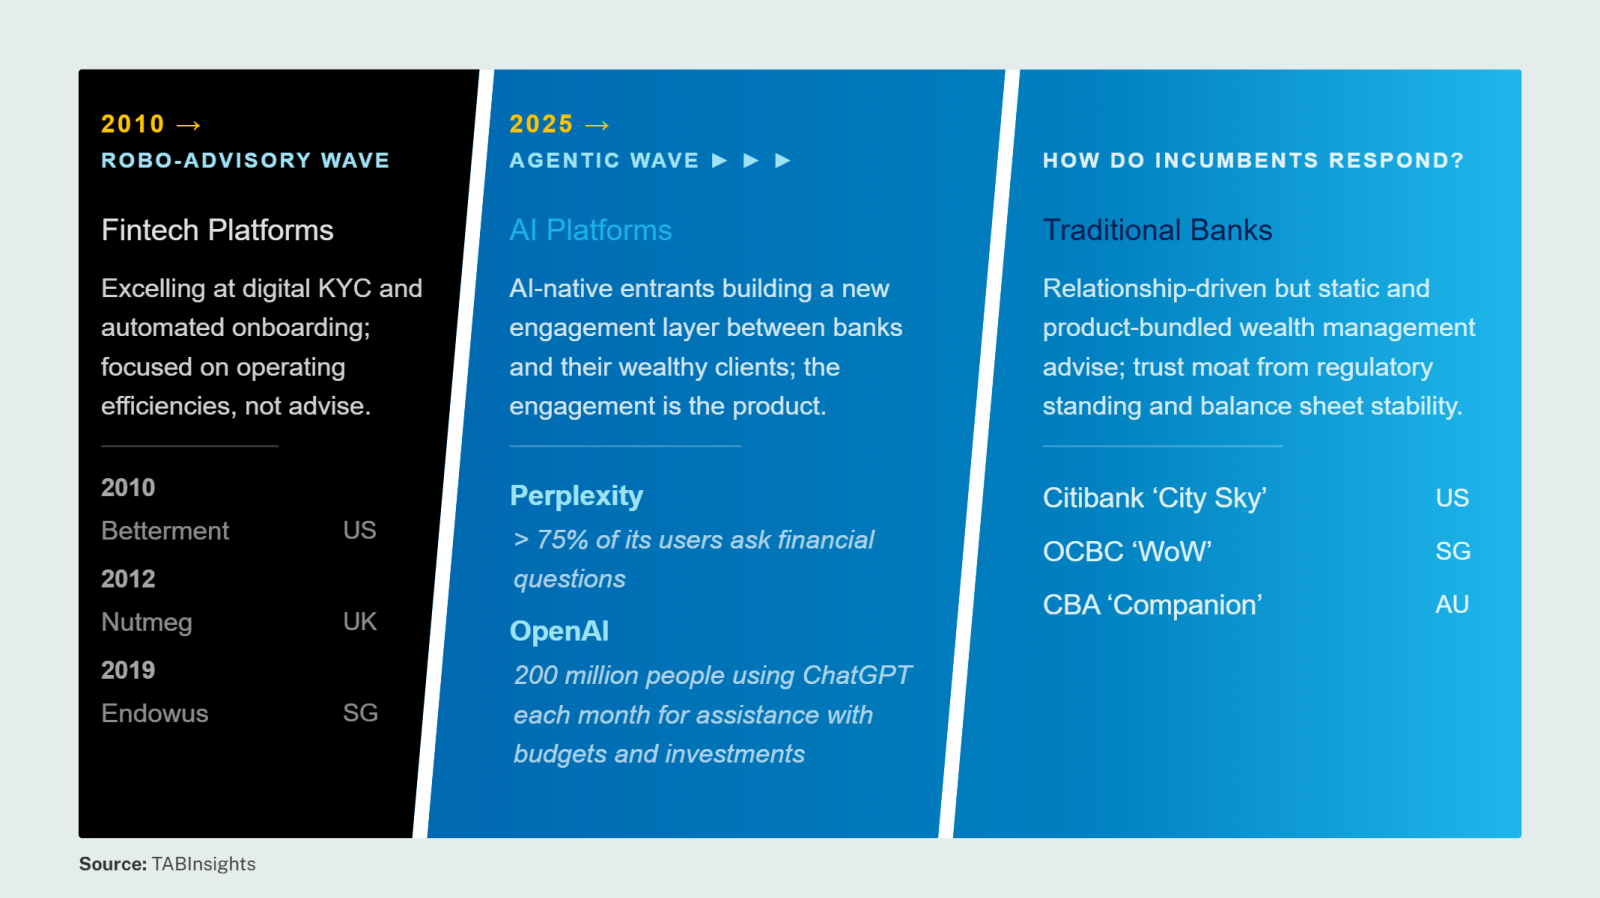
Banks overcame the robo-adviser challenge by retaining control of the client relationship. The next battleground is the financial conversation itself, as AI platforms become the primary interface through which customers seek advice, interpret information and make decisions.
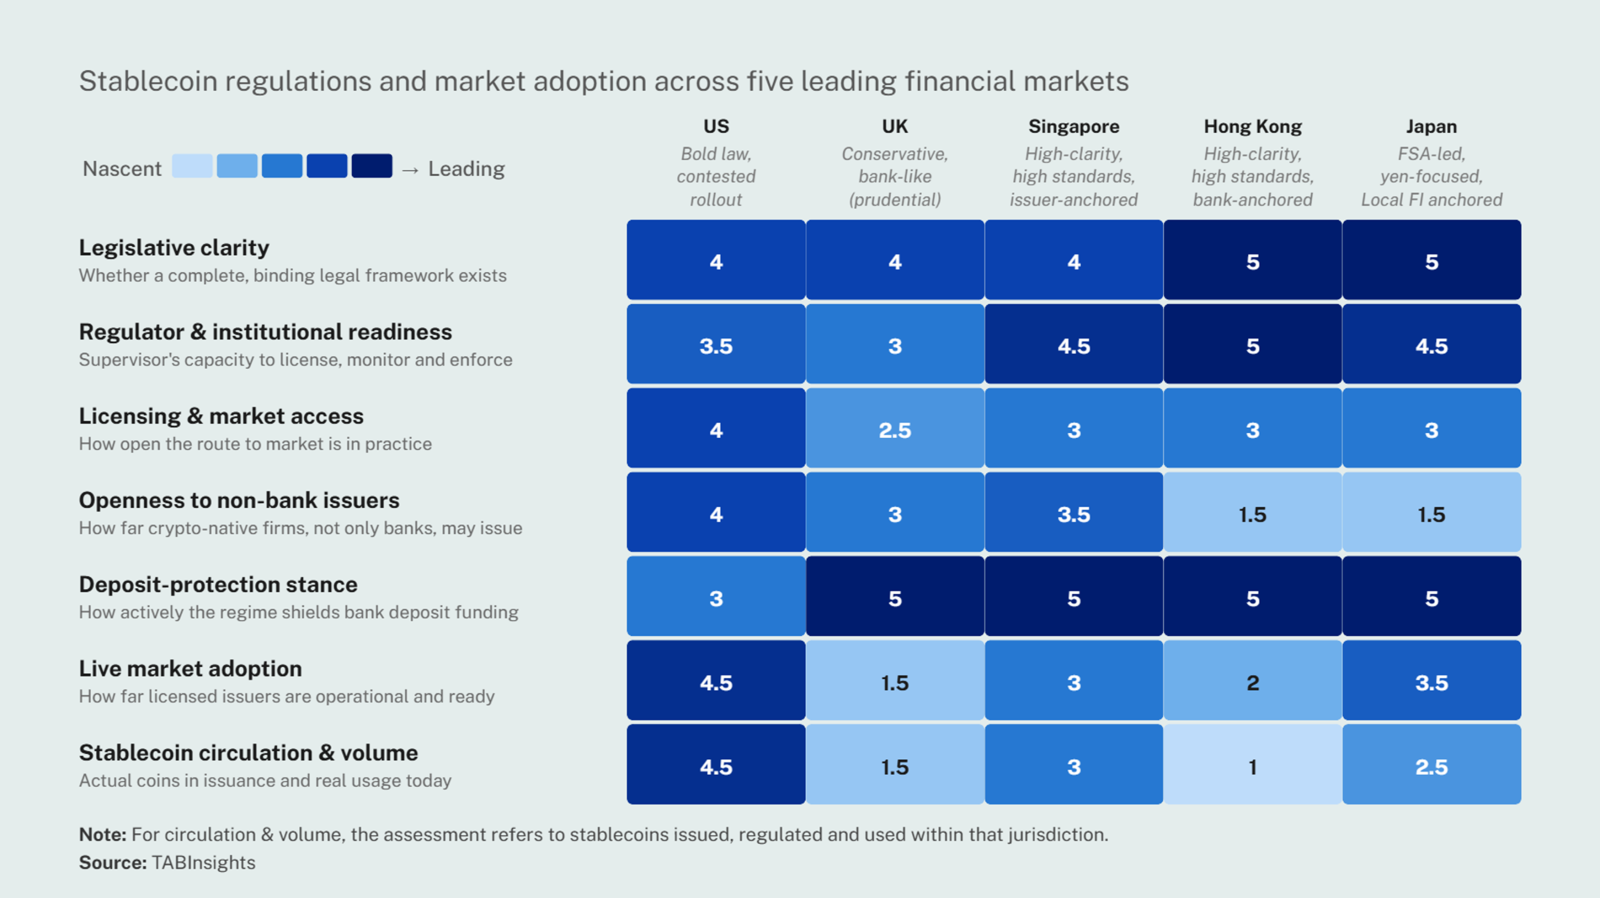
With the July 2026 deadline for US agencies to finalise the implementation of the GENIUS Act approaching, we examine five of the world’s most consequential stablecoin regimes, the United States, United Kingdom, Singapore, Hong Kong and Japan. While these jurisdictions have largely aligned on what constitutes stablecoin, none has yet delivered a commercially scalable market. The real contest has shifted to access, distribution, commercial viability and control—factors that will determine who builds the next generation of payment infrastructure.
© Copyright , TABInsights. All Rights Reserved

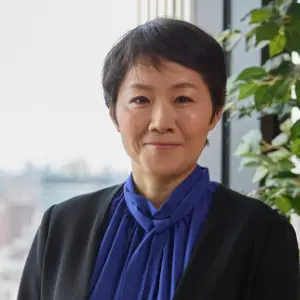
Mai Kaneko leads international business and marketing at DeCurret DCP, a Japanese fintech firm operating a multi-bank network for tokenized deposit under the DCJPY framework. She oversees international expansion initiatives, bank-fintech partnerships and global go-to-market strategy. She holds a Master’s in International Relations from Georgetown University and a Bachelor’s in Economics from University of Tokyo.
Kinoshita has been involved in product development projects across a wide range of industries in Japan, including e-commerce, retail, banking, insurance, and manufacturing. He joined DeCurret DCP in 2024, where he has been engaged in the development of digital currency infrastructure. In addition to building the underlying infrastructure, he supports digital transformation (DX) initiatives associated with the adoption of digital currency solutions across various industries, and promotes projects aimed at enabling cross-border transactions.
Jason Hunt works within ANZ's Industry & Innovation function, engaging with industry challenges, trends and disruptive technologies across payments, digital assets, platforms and data-driven solutions. ANZ was a participant in Project Acacia, the joint Reserve Bank of Australia (RBA) and Digital Finance Cooperative Research Centre (DFCRC) initiative exploring digital money in wholesale tokenised asset markets, which concluded with its final report in May 2026. ANZ has also previously issued its own Australian dollar-denominated stablecoin, A$DC, to settle a real-money digital asset transaction.
Zhu Kuang Lee leads UOB's Innovation Group, formed in April 2025 to consolidate the bank's work across digital assets, data management, blockchain and enterprise artificial intelligence. He represents UOB in regional digital money and tokenisation initiatives, including collaboration with the Monetary Authority of Singapore (MAS), and has described the bank's approach as embedding compliance into system design from the outset rather than adding it later.
Abhinav is currently based in Singapore and leads Client solutions and Sales for Partior. In this capacity, he oversees clients' journeys including commercial and central banks, from defining use cases to product integration. Before taking on this role, Abhinav gained extensive experience working with both global and local banks. He spearheaded transformative initiatives in Payments and Core Banking, requiring him to coordinate efforts across business units, technology teams, and regulatory bodies. Abhinav played a pivotal role in implementing Faster Payments projects throughout Asia, including notable projects like Singapore G3 Fast, Malaysia Duit Now, and Hong Kong FPS. Prior to his tenure in the banking sector, Abhinav served as a Payments Financial Services consultant to various banks and payment fintech companies such as ANZ, Deutsche Bank, and Bank of America. Originally from India, Abhinav holds an Engineering degree and a Postgraduate qualification in Machine Learning and Artificial Intelligence. He is also a dedicated father of two, and he enjoys spending his weekends playing tennis and cherishing moments with his family.
Sakae Hamasaki joined Sanwa Bank (currently MUFG Bank) in April 1993 and worked in corporate banking across five domestic locations. From 2006 onward, he gained extensive experience in the planning, development, and sales of payment-related services for corporate clients in Japan and overseas. He joined DeCurret DCP in 2022, where he has been leading initiatives to support banks in evaluating the adoption of tokenized deposits, as well as collaborating with overseas partners to build cross-border networks utilizing tokenized deposits.
Anouska Ladds is Executive Vice President of Commercial & New Payment Flows, Asia Pacific at Mastercard, based in Singapore. With over 17 years at Mastercard, she has held senior roles across sales, strategy, operations, market development, consultancy, and product development, spanning Asia Pacific, Europe, the Middle East, and Africa. Previously at Barclaycard, she specialised in strategy, customer experience, communications, and SME/acquiring businesses.
David is a seasoned technology executive with significant experience and has over 25 years' experience in CISO and CIO roles across different industries and countries. David has served as a CIO spans across multiple industries and geographies. He was winner Australia CIO of the Year for driving CUA's Transformation. Also, David was CISO for HSBC and Global Head Technology, Cyber and Data Risk Macquarie Group.
A regular conference keynote speaker and thought leader he writes for CIO, CSO, Computerworld and Australian Institute of Company Directors (AICD). His best-selling book - the Aspiring CIO & CISO was published in June 2024 and his second book A Day in the Life of a CISO launched in October 2025 and is already best seller in UK, Singapore, Japan and Australia.
Johnson is a seasoned executive and data and AI leader with over 15 years of experience across the public and private sectors. He is currently Assistant Chief Executive at IMDA, where he helps shape Singapore’s digital future and advance the digital economy. He has held senior data and AI roles in regional banking and global consulting, and began his career in defence and critical infrastructure.
A distinguished leader who has spent over two decades shaping the future of technology and digital finance. Barani Sundaram has held senior leadership positions across Dubai, Singapore, Malaysia, India, and Vietnam, building an impressive track record of delivering large-scale technology transformations across diverse and dynamic markets. As Chief Technology Officer of EastWest Bank in the Philippines, Barani has been instrumental in modernizing the bank's core technology infrastructure, elevating its cybersecurity posture, and championing the adoption of Artificial Intelligence and machine learning. Under his leadership, EastWest Bank has harnessed AI to enhance customer experiences, strengthen fraud detection, and enable data-driven decision-making — while ensuring the highest standards of cyber resilience and regulatory compliance. His strategic vision, technical expertise, and ability to navigate complex challenges have earned him recognition as a pivotal force in shaping intelligent and secure digital banking in the Philippines.
Daniele Tonella is Chief Technology Officer (CTO) and member of the Management Board Banking since August 2024. Daniele is responsible for overseeing and managing the total IT landscape and advising on technology-driven business opportunities. Daniele is a member of the Tech Advisory Board of The Hg Foundation. He holds an engineering MSc from the Swiss Federal Institute of Technology in Zurich (ETHZ) and completed various executive education programmes at Harvard, IMD, INSEAD and MIT Sloan.
Virag Masuraha is a seasoned executive with over 25 years of experience leading Fraud, Financial Crime, and Risk functions for top U.S. financial institutions. He is widely recognized for driving strategic initiatives that reduce costs, enhance profitability, and enable sustainable growth, while successfully managing complex regulatory engagements.
Currently, Virag serves as Managing Director of US AML Financial Crime Modeling at Bank of America. Prior to this role, he held leadership positions at Citi and PNC, where he spearheaded global fraud and anti-money laundering (AML) analytics and modeling functions.
With deep expertise in financial crime and fraud data, analytics, and modeling, Virag has led enterprise-wide strategies in advanced analytics—including big data, AI/ML, entity linkages, network analysis, and machine learning—alongside cyber and digital fraud prevention across consumer and commercial portfolios.
Virag holds an MBA from the Kellogg School of Management and a Master’s in Engineering from Vanderbilt University.
Jackson Oh is the Chief Technology Officer at ANEXT Bank, where he leads the bank’s technology strategy, architecture, and engineering execution as ANEXT scales its digital banking platform for local SMEs and foreign business owners in Singapore.
With close to two decades of experience across banking, fintech, and enterprise technology, Jackson brings a rare blend of deep financial services expertise and hands-on product and platform leadership. Prior to ANEXT Bank, he served as Chief Product Officer at Tribe Fintech and held senior technology and product leadership roles at 360F, SunGard (now part of FIS), AirWatch by VMware, Samsung Electronics, and Bank of America.
Jackson has led large-scale, cloud-native platforms across corporate banking, payments, capital markets, and SaaS environments. He is passionate about building resilient, scalable financial infrastructure, and enabling innovation while meeting the realities of regulatory and operational complexity.
 Google
 LinkedIn